Macro Finance: Global Markets, Policy & Economic Trends
How Big Financial Forces Shape Strong Economies
For a long time, the world of money seemed well-organized.
Central banks paid attention to jobs and inflation. Regulators checked on banks to make sure they were safe. Financial markets were important, but they stayed within their own space. Then, in 2008, that clear separation came crashing down. When the global financial crisis hit, it became clear that finance and the real economy were deeply connected. From that moment, a new way of thinking emerged: macro finance.
At its core, macro finance looks at how money flows through the whole economy and how financial markets and economic growth influence each other.
It recognizes something that now seems obvious but wasn’t before: finance doesn’t just follow the economy—it helps drive it. Investor feelings, credit spikes, interest rates, and asset prices don’t just watch from the side. They affect hiring, spending, investment, and long-term plans.
The roots of macro finance come from a simple but worrying idea.
When things feel stable for too long, people take more risks. Economist Hyman Minsky warned that calm periods can lead to careless borrowing. Businesses take on more debt. Households stretch their money. Everything looks fine—until it suddenly isn’t. When debt builds up quietly, even a small shock can cause big damage. This cycle of confidence, risk, and collapse is a main concern of macro finance.
What makes macro finance different from older methods is what it focuses on.
Traditional regulation often checked if individual banks were safe. Macro finance asks a bigger question: what happens if everyone panics at once? Instead of looking at one bank, it studies the whole system. It tracks how risks spread, how asset sales can get out of control, and how fear can move faster than facts.
This shift became clear after the 2008 crisis, when stress tests replaced simple rules.
These tests don’t just look at past behavior. They imagine future disasters. They ask if banks could survive big recessions, market crashes, or sudden rises in unemployment. That forward-thinking approach is a key part of macro finance.
The tools of macro finance are also different.
It’s not just about changing interest rates anymore. Policymakers now use tools designed to cool down hot credit markets before they blow up. These include limits on how much people can borrow compared to asset values, higher capital requirements during good times, and mandatory stress tests. These tools don’t target inflation directly. Instead, they aim to smooth out dangerous financial swings—another core goal of macro finance.
Over time, this has quietly changed what we expect from central banks.
They are no longer just protectors of prices and jobs. They are also keepers of financial stability. And understanding macro finance isn’t just for policymakers anymore. Investors need it too.
Think back to the years when interest rates were near zero.
Stocks went up, even though company profits didn’t grow much. Why? Because low interest rates made future earnings more valuable now. That basic idea is at the heart of macro finance. Anyone managing money without paying attention to macro finance might miss why markets move together—or why tech companies and government bonds sometimes go up and down at the same time.
Once you look at the world as a whole, macro finance becomes even more complex.
When the U.S. economy gets stronger, the dollar usually rises. Since global trade and borrowing depend on the dollar, that strength spreads worldwide. For emerging economies, this can be tough. Higher U.S. interest rates can tighten financial conditions abroad—even when those countries are already struggling. Macro finance helps explain why local choices can have global effects.
Climate change adds another layer.
Moving away from high-carbon industries isn’t just an environmental issue—it’s a financial one. Repricing assets tied to fossil fuels affects pensions, insurance companies, and public budgets. Central banks in over 100 countries now see climate risk as a major threat. Through the lens of macro finance, climate shocks aren’t distant problems—they are financial risks that can shake up entire economies.
Then there’s digital money.
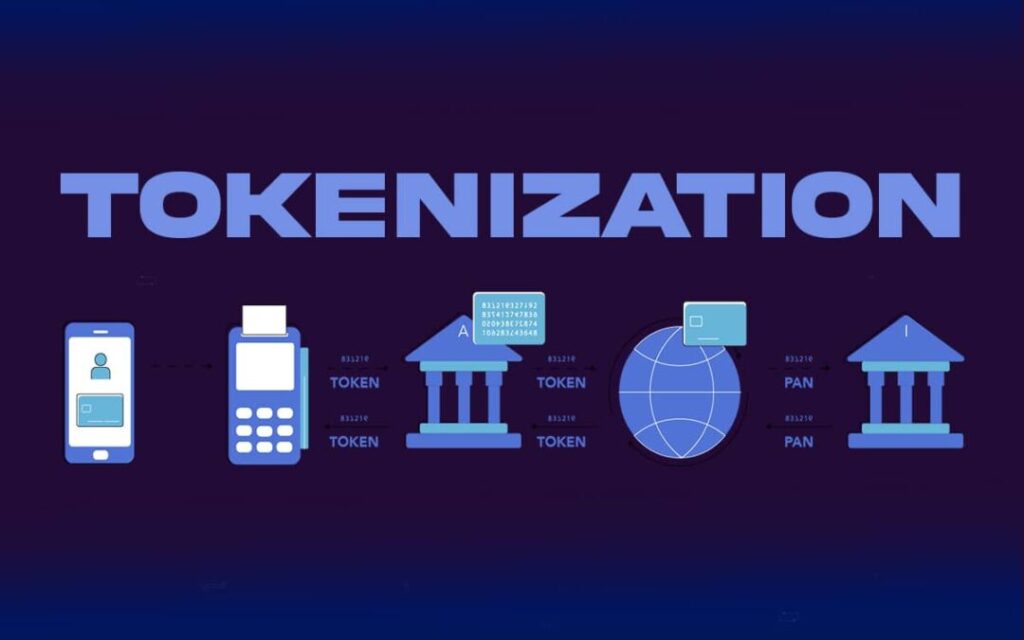
As digital currencies and central bank digital money grow, they could change how savings and banking work. If people move money out of traditional banks and into digital wallets, how interest rates affect lending could change completely. This isn’t a small change—it’s a big shift that macro finance must deal with.
Some critics say macro finance just restates the obvious—after all, finance has always mattered.
But that misses the point. Macro finance is about measurement, not just ideas. It asks specific questions. How much does a rise in credit spreads slow economic growth? How much do market swings affect business investment? These answers matter, and guessing isn’t good enough anymore.
Looking ahead, macro finance faces big challenges.
As governments take on more debt in a world without cheap borrowing, trust between countries, banks, and investors will be more important than ever. Global investment may become fragmented as countries focus more on security than efficiency. Technology could make economic data more accessible while also giving more control over who owns it. Each of these changes will shape how macro finance works.
One thing has stayed the same since the last crisis: managing macro finance isn’t just about following rules.
It’s about building confidence. Money only works when people believe in it. Loans, trust, and resources are all connected. If one is missing, the whole system slows down.
In the end, macro finance teaches us something simple but powerful.
The economy isn’t a machine with separate parts. It’s a living system held together by belief, behavior, and balance. To understand it, we have to see the big picture—every time.